
A ten-year-old sedan worth roughly $4,000 and a two-year-old SUV worth roughly $30,000 should not carry the same protection, yet plenty of drivers insure both the same way. One premium difference is a few hundred dollars a year; the other is a potential four- or five-figure repair bill. The honest answer about saving money depends on the car, the loan, and how much cash sits in the household.
What each shape actually pays for
Liability coverage pays other people when you cause a crash: their injuries, their vehicle, and sometimes a fence or a storefront. It does not repair your own car. Physical damage coverage, usually sold as collision plus comprehensive, repairs or replaces your vehicle after a crash, theft, hail, fire, or a broken windshield, minus the deductible. State rules generally require the first kind; a lender usually requires the second as long as a loan is outstanding.
That split explains most of the price gap. A liability-only plan behaves like protection against a large claim you caused to someone else. A fuller plan adds a second layer that protects your own asset. Where the first is cheap and legally necessary, the second is a bet on whether the car is still worth insuring against its own repair costs.
A quick test with real numbers
Take the annual cost of the physical damage portion, add the deductible, and compare that total with what the car would realistically fetch in a private sale. If the coverage runs roughly $600 a year with a $1,000 deductible on a vehicle worth around $3,000, you are paying a substantial fraction of the car's value each year for protection that can only pay out once. The arithmetic rarely favors keeping it.
On a financed or leased vehicle the calculation changes completely. The lender is a co-owner in everything but name and will require physical damage coverage until the balance is cleared. Dropping it early can trigger a forced-placed policy, which is usually more expensive and protects the lender's interest rather than yours. Check the loan agreement before touching the coverage.
Costs that sit outside the premium
Repair bills do not disappear because a policy was trimmed. A driver who keeps a car long enough will eventually face a cracked windshield, a parking lot dent, or a deer at dusk. With only liability, those bills are paid entirely out of pocket. Some households handle that comfortably by setting aside the premium saving every month; others discover the saving was spent long before the repair arrived. A separate savings buffer is what makes the choice deliberate.
There is also the question of how a claim gets valued. If another driver is clearly at fault and insured, their liability coverage should handle your repairs. If the other driver is uninsured or never identified, your own policy is the only route unless you carry specific coverage for that situation. Ask about that gap explicitly before deciding the cheaper plan is enough.
A workable rule for most households
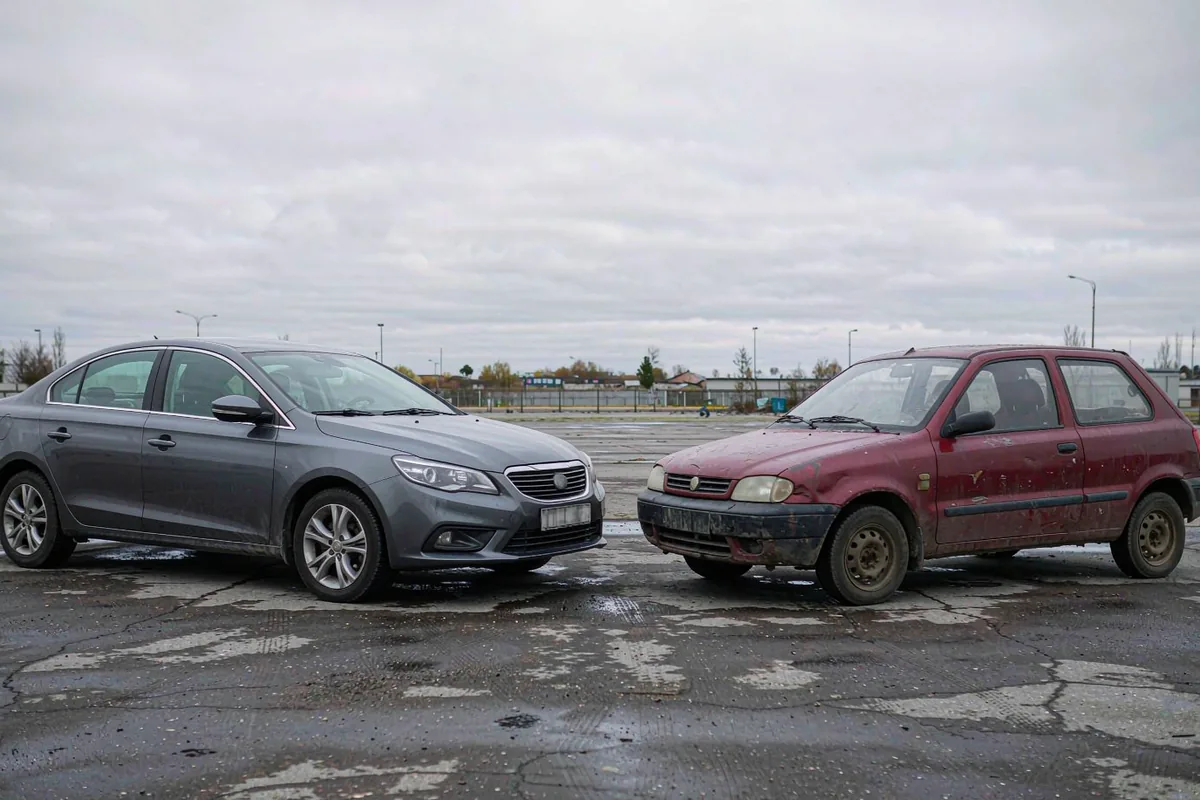
Keep physical damage coverage while the car is financed, while its market value would be genuinely painful to replace, and while a single repair would disrupt the household budget. Consider dropping it when the vehicle is older, paid off, and the annual premium plus deductible approaches a large share of its value. Revisit the decision at each renewal rather than treating it as permanent.
Whatever you choose, raise the liability limits before trimming anything else. The expensive scenario is rarely a dented bumper; it is a serious injury claim that outruns a state minimum. Saving a few hundred dollars a year is a poor trade if it leaves the biggest exposure in the household underinsured.